Saudi Arabia Needs an Overland Route to Global Energy Markets
Saudi Arabia’s sea-based export strategy has increasingly come under pressure from regional spoilers, and a land-based route stretching north to Europe is an enticing alternative.

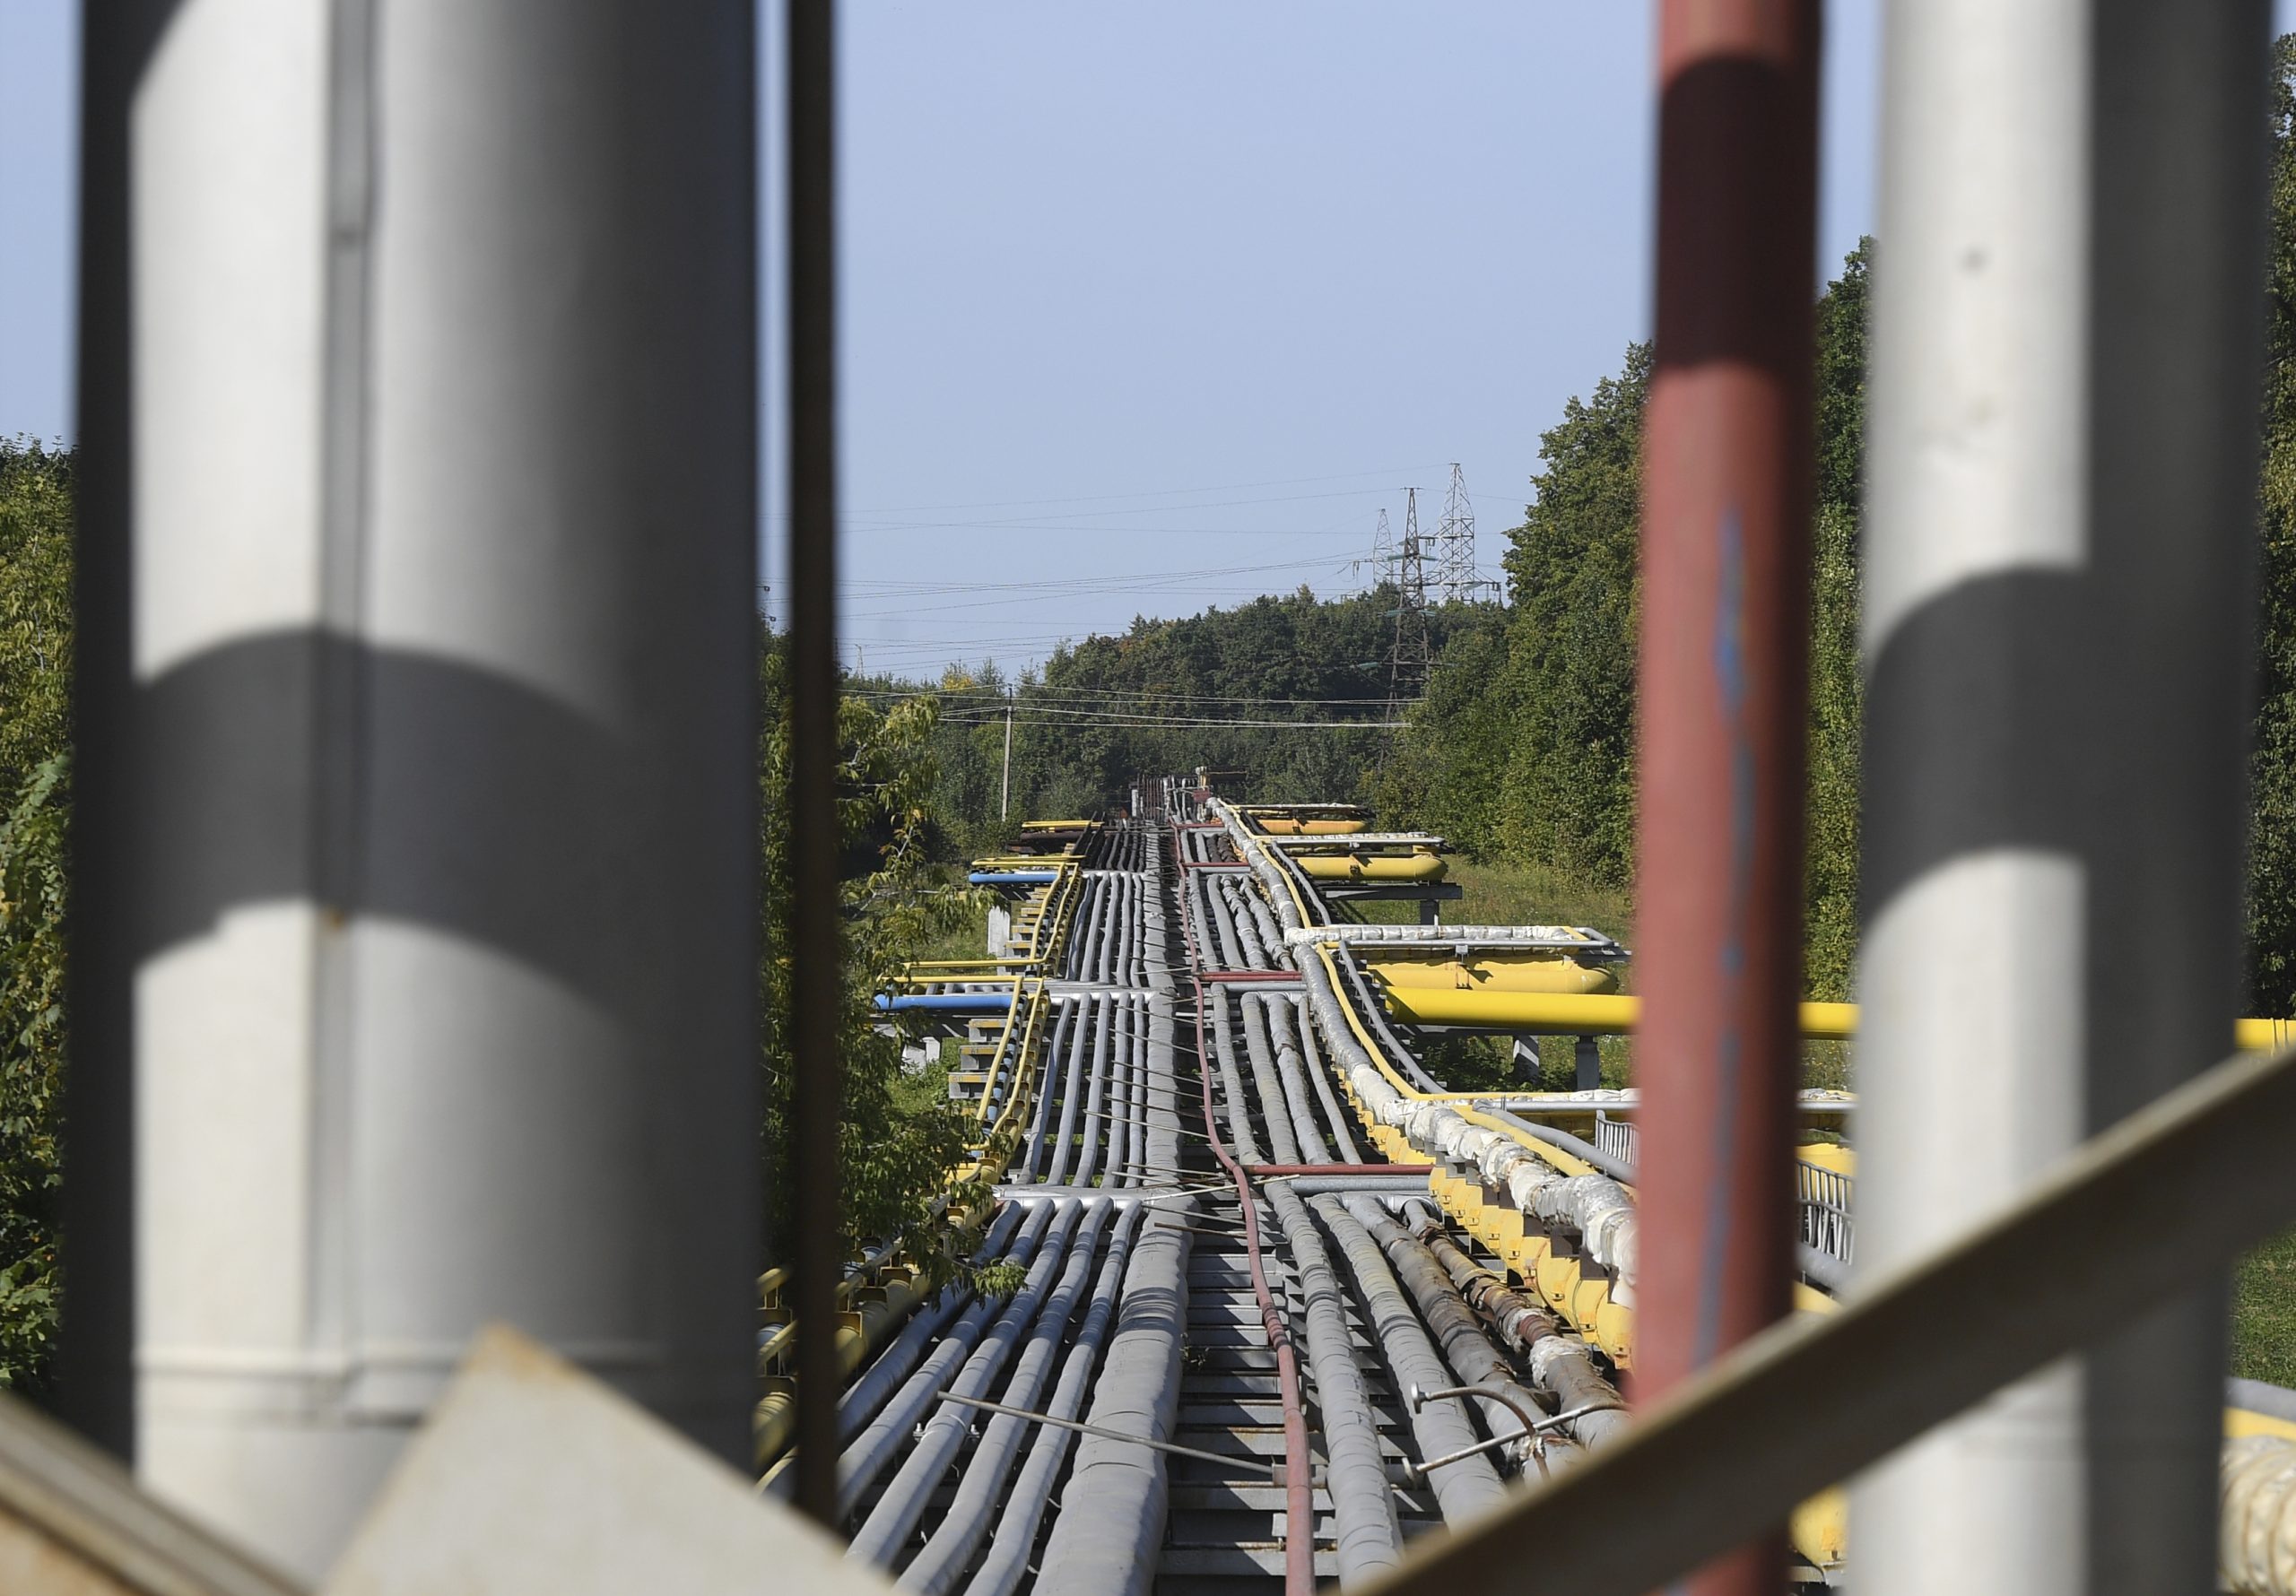
For years, Saudi Arabia has recognized the vulnerability created by its dependence on the Strait of Hormuz. To reduce risks from Iranian disruptions, the kingdom built the East-West pipeline, which links its eastern oil fields to the Red Sea port of Yanbu. The pipeline provides Riyadh with a strategic alternative export route that bypasses the Strait of Hormuz and has helped sustain Saudi exports throughout the ongoing war in the Gulf.
While this strategy has provided an important safeguard during the past several months, it has a major flaw: it merely shifts Riyadh’s dependence from one vulnerable maritime route to another. Iranian disruptions to shipping through Hormuz and Houthi attacks in the Red Sea have together exposed the limits of that approach. Looking forward, what Saudi Arabia, other Gulf states, and Iraq need most is an overland route to Europe.
A New Plan Emerges
Beyond the East-West pipeline, Saudi Arabia has been exploring new ways to diversify its export routes. In recent weeks, commercial and diplomatic efforts have focused on a proposed Yemeni pipeline that would bypass Hormuz. Yet Yemeni instability and opposition from the Houthis, who are backed by Iran, have buried the project in uncertainty.
Another potential pathway is the Four Seas Initiative. The initiative would connect the Gulf, the Caspian Sea, the Mediterranean, and the Black Sea through an overland energy and infrastructure network centred on Syria and Türkiye. Large parts of this network already exist. For Saudi Arabia, the central component is the Gulf–Mediterranean corridor: a modern expansion of the old Tapline logic that would move Saudi and Gulf energy through Jordan and southern Syria to Banias on the Mediterranean. From there, energy could enter wider distribution networks serving lucrative European markets.
The plan should not be viewed merely as a Syrian reconstruction plan or another abstract connectivity scheme. It represents a potential next stage of a Saudi energy strategy, providing leverage and flexibility for Riyadh’s oil sector, its allies, and global markets. The initiative is also structured to maintain legal, governance, and financial support, including U.S. and EU engagement.
Security, Incentives, and Viability
The Four Seas corridor does not eliminate Iran’s capacity for disruption, but it does reduce its leverage over any single chokepoint. Today, Tehran can threaten to close a single strait and hold global energy markets hostage. An overland route through Syria and Jordan removes that veto.
Iran would still retain other methods to push back. It has long supported armed groups in Iraq that operate close to the proposed Kirkuk–Deir ez-Zor pipeline route, and its networks inside Syria, though weakened since Assad’s fall, have not disappeared. Tehran has also spent decades blocking Caspian energy agreements outside its control. None of this is fatal to the project. The Trans-Anatolian Pipeline has moved Azerbaijani gas to Europe for years through a similarly turbulent environment. But the framework only works if it is backed by coordinated intelligence among transit states and a clear U.S. commitment to respond to interference.
There is also a deeper logic at play. Once Syria and Iraq begin earning billions in transit revenues, they gain a direct economic stake in keeping the system operational. That shifts the incentive structure in ways that no military guarantee alone can replicate.
For a corridor of this scale to function, every country along the route must see it as serving its own interests, not as a favor to Washington or Riyadh. Jordan gains transit revenues and construction investment at a moment when it can ill afford to turn either down. Syria gains something more fundamental: a durable revenue base. Transit fees alone, conservatively estimated at $3 to $6 billion annually, would give Damascus more fiscal breathing room than any aid package on offer. Iraq reduces its dependence on vulnerable Basra terminals exposed to Gulf instability, with a new pipeline to the Mediterranean carrying up to 1.4 million barrels a day reshaping its export calculus. Türkiye advances its longstanding ambition to become a regional energy hub, with corresponding leverage over European markets. The UAE and Kuwait, like Saudi Arabia, gain an export route that does not depend on Iran’s goodwill at the Strait of Hormuz. What makes this different from earlier connectivity plans is simple: every actor has a material stake in its success.
The scale of the project would place it among the world’s major energy infrastructure networks. The Gulf–Mediterranean corridor is projected to carry 1.5 to 2 million barrels of oil per day, while the wider Four Seas system could move 3 to 4 million barrels per day and 40 to 50 billion cubic metres of gas annually toward Mediterranean and European markets. This capacity would make the corridor a major addition to Saudi Arabia’s energy export infrastructure and underscores the country’s broader conviction that a major energy power should not be dependent on any single maritime chokepoint. Riyadh has already applied this logic domestically through the East-West pipeline, and the Four Seas Initiative extends that same principle northward.
A fair question remains: will hydrocarbons justify the infrastructure by the time it is completed? The short answer is yes, but the longer answer is more important. Even the most ambitious net-zero scenarios project strong oil and gas demand well into the 2030s, providing sufficient time for the corridor to recover its costs. Beyond that, the infrastructure is not a stranded asset. Pipelines, compressor stations, and cross-border grid connections can be converted to carry hydrogen, a process already underway across European gas networks built decades ago. The logic is not a bet against the energy transition, but a way of using hydrocarbon revenues to pay for it.
Syria as the Catalyst
Within this broader incentive structure, Syria functions as the critical land bridge between the Gulf and the Mediterranean. If Syria can be rebuilt as a corridor for trade, energy, telecommunications, and transport, Saudi Arabia would gain a more stable northern commercial environment and new investment opportunities aligned with the kingdom’s transformation agenda.
Saudi investment in Syria’s aviation, energy, telecommunications, real estate, and water infrastructure shows that Riyadh recognizes the window of opportunity. The Four Seas Initiative provides a framework that could make these investments more profitable and sustainable while supporting the logistics, industrial, and infrastructure networks required for Vision 2030. Achieving those goals will require greater diversification and closer links with neighboring states.
The Corridor in a Multipolar System
The Four Seas Initiative’s longer-term “Five Seas” logic is that, once the Four Seas energy corridor is established, the same connectivity could extend southward through the Red Sea. This would link Jeddah, Aqaba, Aden, Djibouti, Port Sudan, and the Suez zone into a broader economic network that could draw greater financial and commercial activity toward Jeddah and its surrounding regions.
Beyond its economic value, the corridor would also shape the strategic balance of the region. While the corridor is mostly discussed as a European energy story, it matters just as much for Asia. China, India, Japan, and South Korea already absorb the bulk of Gulf crude, and nothing about the Four Seas Initiative changes that. What it does change is the negotiating dynamic. Right now, Gulf producers have relatively little leverage with Asian buyers, because Asia is essentially the only large market accessible to them at scale. A working overland route to Europe changes that quietly but fundamentally. Riyadh would finally have a credible alternative destination for its oil, not because it plans to abandon Asian customers, but because having the option transforms the relationship. The difference between a supplier with nowhere else to go and one with a genuine alternative is the difference between a dependency and a partnership.
China has spent years expanding its infrastructure presence across the Middle East and Central Asia, and Saudi Arabia has a strong interest in ensuring that the future of Levantine energy infrastructure is not shaped solely by Chinese state firms. Despite its friendly relations with Beijing, Riyadh has sought to position itself as a key player in shaping the post-Assad regional order, including the infrastructure and economic networks that will define the region’s future.
Russia will recognize the Four Seas Initiative for what it is: the southern extension of the Three Seas framework that did more to erode its influence in Europe than anything else in the past decade. Moscow still has cards to play. It keeps a naval base at Tartus, retains energy influence over Ankara, and can work through its Iranian relationships to slow Caspian corridor development. None of this should be underestimated. But the Three Seas Initiative offers a clear precedent: once Washington put its full political weight behind the project, the cost of Russian interference became too high to justify. The same dynamic would apply here. This is why the formal institutional architecture—the ministerial forum, the multilateral financing vehicle, the U.S. endorsement—matters as much as the pipelines themselves. Bilateral deals can be picked apart one by one but a transatlantic framework is much more resilient.
The kingdom has spent years building the foundations of a post-oil economy while remaining one of the world’s indispensable energy powers. Its energy strength gives it the capital, relationships, and strategic weight needed to build the infrastructure of a wider regional energy system. Saudi Arabia should not wait for others to define the northern corridor. It should help build, finance, and govern it from the beginning.
The views and opinions expressed in this article are those of the authors and do not necessarily reflect the views of Gulf International Forum.
Issue: Energy & Environment
Country: GCC, KSA
Dr. Azeem Ibrahim, OBE, is the Chief Strategy Officer at the New Lines Institute for Strategy and Policy in Washington, D.C. He received his Ph.D. from the University of Cambridge after which he completed fellowships at the universities of Oxford, Harvard and Yale. He has advised a number of world leaders and governments on policy development and strategy, including the 2021 Integrated Defence and Security Review and as a member of the 2021 G7 Leader’s Panel on Economic Resilience. He is a columnist at Foreign Policy magazine and the author of four award-winning books including “Authoritarian Century: Omens of a Post-Liberal Order” (Hurst:2022)
Dr. Dania Arayssi is a Program Head and Senior Analyst at New Lines Institute for Strategy and Policy, where she leads the Four Seas Project as well as the Central Asia Center, in addition to analysis of the dynamics of political economies in Lebanon, Syria, and the broader Middle East. Her research work focuses on political behavior, institutional trust, economic vulnerability, and the political effects of remittances. Arayssi also engages directly with U.S. policymakers and institutional stakeholders, producing analyses that inform congressional and executive branch decision-making. Arayssi also serves as an adjunct assistant professor at Georgetown University’s Edmund A. Walsh School of Foreign Service and teaches at George Washington University. Before joining New Lines, Arayssi held analytical and research roles with the World Bank, USAID, Oxfam America, and the U.S. Army War College. Her work has been published by Foreign Policy and the Digest of Middle East Studies as well as regional and international media outlets. She holds a Ph.D. in Political Science from the University of Colorado-Boulder and master’s degrees in the history of international relations, public policy, and political science, as well as a bachelor’s degree in international affairs.
Cartel at Dusk: OPEC’s Future After the Iran War
July 28, 2026Something more consequential than another oil market disruption is underway. The Iran war has exposed and accelerated an institutional weakness within OPEC that had been…
It’s Time for a Climate OPEC
June 29, 2026Many developments are converging to make climate policy an urgent priority in the Gulf, but the most recent crisis, the U.S.-Israeli war with Iran, risks…

From Hormuz to the Four Seas: Iraq’s Search for Energy Security
June 12, 2026The Iran war has had a tremendous impact on the global economy, but few countries have been as exposed to the energy crisis as Iraq….